

Key Events: Economic data appears resilient
While the headline PCE inflation data exceeded 4%, core PCE for the month of May came in at 0.3% month-on-month and 3.4% year-on-year, in-line with expectations. Income and spending both rose by 0.7% and first quarter GDP was revised higher.1 Oil prices declined ed further on the week, providing additional relief on the inflation front.
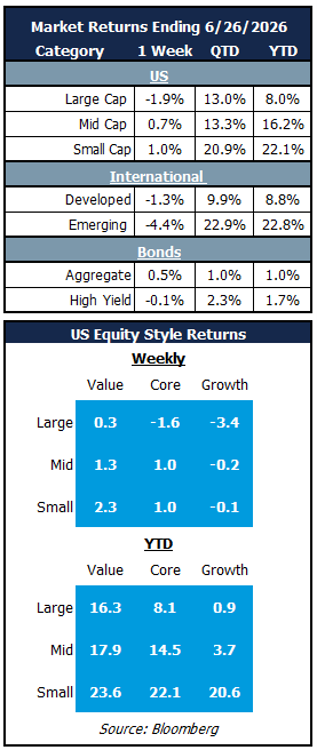
Market review: Equal-weight shines in down week
The S&P 500 shed 1.9% on the week, but 8 out of 11 sectors were positive and the Equal-weight S&P 500 advanced 1.6%. Value outperformed growth and small and mid-cap stocks outperformed large caps with large-cap tech stocks down over 5%. International equities declined, with emerging markets falling in concert with US large cap tech stocks.
On the fixed income side, the broad bond index advanced as yields fell, while high yield weakened on wider spreads.
Outlook: Broadening theme resurgent
One of our central investment themes entering 2026 was the expectation that market leadership would broaden beyond the narrow concentration in large-cap tech that defined recent years. That thesis gained early traction, but the uncertainty surrounding the Iran conflict disrupted many of the sectors poised to benefit.
Over the past several weeks, the broadening theme has reemerged. Valuation spreads widened, concerns over evaporating free cash flow for the Mag-7 stocks have taken hold, and declining oil prices – aided by the memorandum of understanding with Iran – have provided a meaningful tailwind for a wider range of companies and sectors.
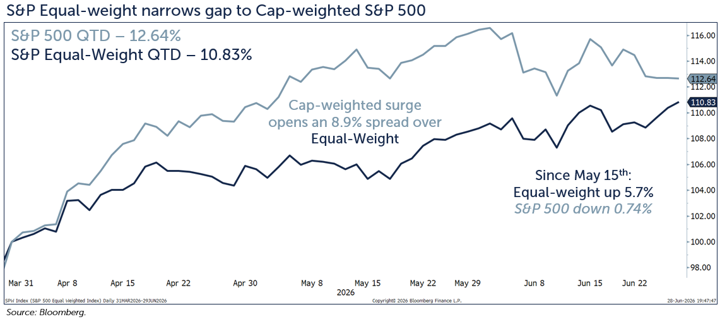
The result has been a tale of two halves for the second quarter. The Equal-weight S&P 500 has recaptured most of the performance gap from the first half of Q2 as shown in the exhibit below. This is a useful reminder of why discipline and diversification matter most when the market becomes too narrowly focused on a single investment outcome. Chasing recent winners tends to lead to regret. Staying committed to a sound, long-term plan builds the confidence required to avoid unnecessary turnover and to remain invested when it matters most.
Tale of Two Halves for the the Second Quarter
OneAscent Navigator Outlook: June 2026
This material is intended to be educational in nature, and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.2
1) Source: Bloomberg data.
2) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield
OAI01560