

Key Events: Benign inflation, more Hormuz tension
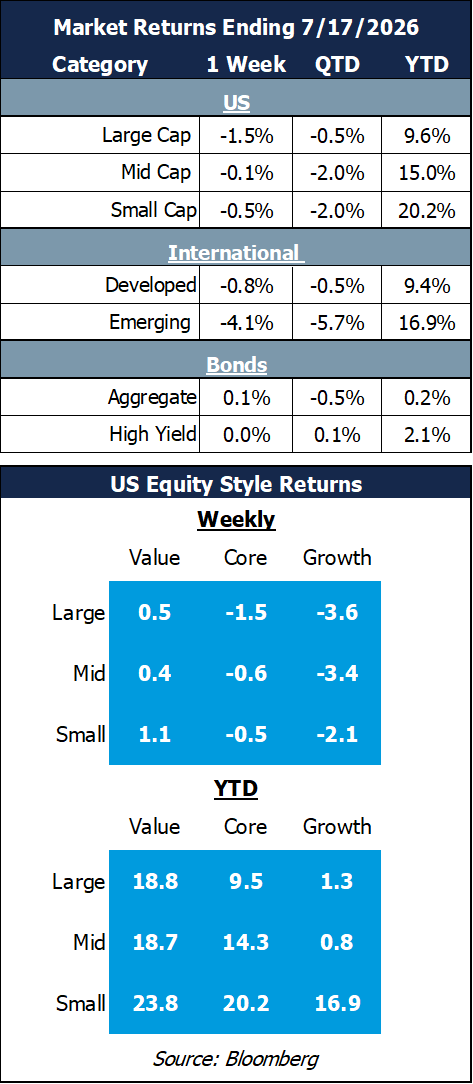
Geopolitical risk moved back to center stage as U.S. strikes on Iran extended into a ninth consecutive night, ending the fragile ceasefire and pushing oil higher for a second straight week. The renewed hostilities were offset by declining inflation readings which nudged rate expectations slightly lower.1
Market review: Semiconductors lead a tech selloff
The S&P 500 lost 1.5%, led by a 10% decline in semiconductor stocks as the market reassessed the excitement over AI-related names. Mid and small-cap indices, less exposed to the AI theme, held in better while emerging markets, which are more exposed to chipmakers, led the declines.
Outlook: Shifting stock market return drivers
There was encouraging news underneath the headline of the semiconductor, AI-driven selloff. Several other sectors showed positive returns and, as the chart below illustrates, 2026 returns have been driven by earnings, not multiple expansion. This is positive news for those who focus on long-term returns.
We are beginning to see a rotation into sectors beyond large cap technology, which is precisely why we diversify across sector, style, geography, and market cap. And while the valuation multiple compressed, the mirror image of the multiple-driven 2023–24 rally, growing earnings provide a healthier foundation.
A lower P/E multiple only looks cheap if the company earnings prove durable, so we will be watching this quarter’s earnings closely; expectations are for 22.8% growth for the “other” 493 stocks outside the Mag-7. The first week of earnings season has been strong, driven by solid results in financials.
Our counsel is unchanged: adhere to your objectives, stay diversified, and let discipline carry you through the noise rather than chasing last quarter’s winner.
Strong earnings growth is offset by multiple contraction
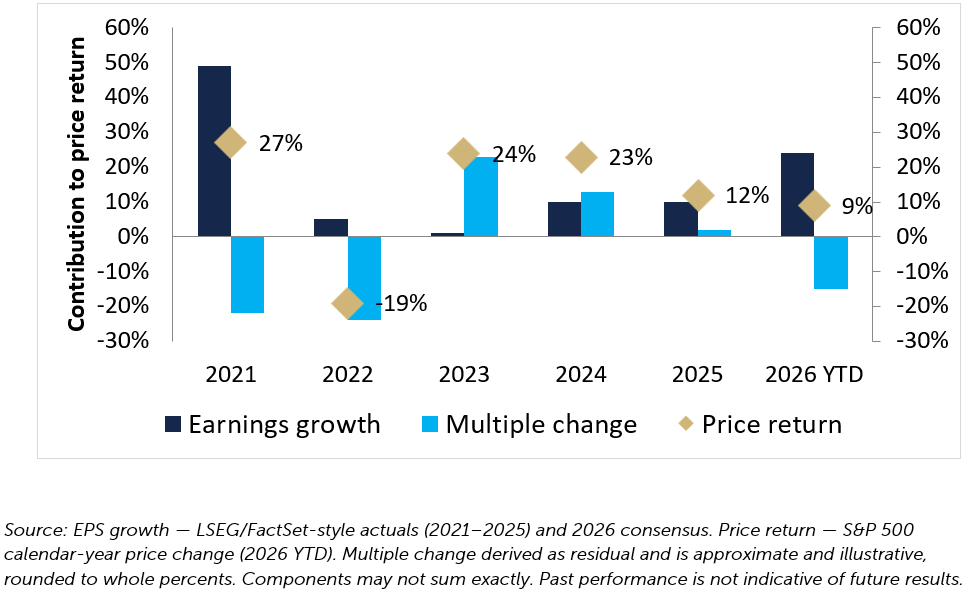
OneAscent Navigator Outlook: July 2026
This material is intended to be educational in nature, and not as a recommendation of any particular strategy, approach, product or concept for any particular advisor or client. These materials are not intended as any form of substitute for individualized investment advice. The discussion is general in nature, and therefore not intended to recommend or endorse any asset class, security, or technical aspect of any security for the purpose of allowing a reader to use the approach on their own. Before participating in any investment program or making any investment, clients as well as all other readers are encouraged to consult with their own professional advisers, including investment advisers and tax advisors. OneAscent can assist in determining a suitable investment approach for a given individual, which may or may not closely resemble the strategies outlined herein.2
1) Source: Bloomberg
2) Market Returns reference the following indices: Large Cap – S&P 500, Mid Cap Growth – Russell Midcap growth, Mid Cap Value – Russell Midcap Value, Small Cap – Russell 2000, Developed – MSCI EAFE, Emerging – MSCI Emerging Markets, Aggregate – Bloomberg US Aggregate, High Yield – Bloomberg High Yield